Share this Post
Open Enrollment: Are You Making the Most of Your Employee Benefits?
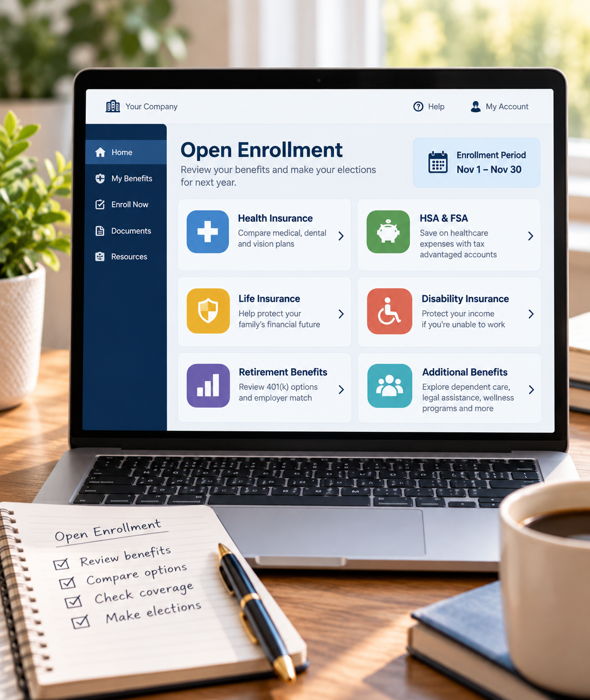
Open enrollment is here again, and for many employees, it's tempting to simply renew last year's benefits without giving them much thought.
However, your employee benefits are an important part of your overall financial picture. Decisions around health insurance, life insurance, disability coverage, and retirement savings can impact your cash flow, taxes, and family's financial security. Taking a little time to review your options can help you identify opportunities to save money and ensure you're adequately protected.
Here are five important areas to consider before making your elections for the upcoming year.
1. Look Beyond the Health Insurance Premium
Health insurance is often the biggest decision during open enrollment, and it's natural to focus on how much will be deducted from each paycheck.
However, the plan with the lowest premium isn't necessarily the least expensive option.
When comparing plans, consider:
- Premiums: How much will you pay throughout the year for coverage?
- Deductibles: How much will you pay before certain insurance benefits begin?
- Out-of-Pocket Maximums: What's the most you could pay for covered, in-network medical expenses during the year, excluding premiums?
- Provider Networks: Are your preferred doctors, hospitals, and prescriptions covered?
One helpful way to compare plans is to add your annual premiums to each plan's in-network out-of-pocket maximum. This gives you an estimate of your potential annual costs for covered, in-network healthcare services in a year with significant medical expenses.
Don't automatically rule out a high-deductible health plan (HDHP). While these plans typically have higher deductibles, they may also have lower premiums and offer access to a Health Savings Account (HSA). Some employers even contribute money to your HSA, which can help offset healthcare costs.
For example, if an HDHP saves you $2,000 annually in premiums and your employer contributes another $1,000 to your HSA, that's a $3,000 advantage before accounting for differences in out-of-pocket medical expenses.
If you're expecting a child, planning a surgery, or anticipating other significant medical expenses, factor those circumstances into your decision.
Take some time to evaluate the total potential cost of each plan rather than focusing solely on the monthly premium.
2. HSA vs. FSA: What's the Difference?
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) both provide valuable tax advantages when paying for healthcare expenses, but they work differently.

Why an HSA Can Be Especially Valuable
An HSA offers three significant tax advantages:
- Contributions are generally tax-deductible or made pre-tax through payroll.
- Funds can grow tax-free within the account.
- Withdrawals for qualified medical expenses are tax-free.
Unlike an FSA, unused HSA funds remain in your account year after year. If your cash flow allows, you can pay current medical expenses out of pocket and leave your HSA invested for future healthcare expenses, potentially allowing the balance to grow over time.
You can also reimburse yourself for qualified medical expenses incurred after establishing your HSA in prior years, provided you maintain appropriate records and haven't already received reimbursement or claimed those expenses as a tax deduction.
An FSA can still be a great option, particularly if you have predictable healthcare expenses or aren't eligible to contribute to an HSA. Just be mindful of your employer's rules regarding unused funds.
One important consideration: Participating in a traditional, general-purpose healthcare FSA generally makes you ineligible to contribute to an HSA. However, some employers offer a limited-purpose FSA, typically covering dental and vision expenses, that can be used alongside an HSA.
3. Is Your Employer-Provided Life Insurance Enough?
Many employers provide basic life insurance coverage at little or no cost, often equal to one or two times your annual salary.
While this is a valuable benefit, it may not be enough to adequately protect your family. Consider someone earning $120,000 annually whose employer provides life insurance equal to one year's salary. That $120,000 could certainly help, but consider everything those dollars might need to accomplish:
- Replace lost income for a surviving spouse and children.
- Pay off outstanding debts, including a mortgage.
- Cover childcare and future education expenses.
- Provide financial stability for years to come.
For a young family, one year's salary may fall well short of what's needed.
Another consideration is portability. Employer-provided life insurance is often tied to your employment. If you change jobs or leave the workforce, you may lose that coverage or have limited options to continue it. This can become particularly problematic if your health changes and obtaining new coverage becomes more expensive or difficult.
Before automatically purchasing supplemental life insurance through your employer, consider comparing the cost and terms with an individual term life insurance policy. Many individual term policies offer guaranteed level premiums for a specified period, such as 20 or 30 years, and remain in place regardless of where you work, provided premiums are paid.
Employer-provided coverage is a great starting point, but it shouldn't automatically be considered your complete life insurance plan.
4. Disability Insurance: The Benefit You Don't Want to Overlook
While life insurance often receives more attention, disability insurance can be just as important.
For most working professionals, their ability to earn an income is one of their most valuable financial assets. What would happen financially if an illness or injury prevented you from working for an extended period? Many employers provide short-term or long-term disability insurance, but having coverage doesn't necessarily mean you're adequately protected.
Here are a few important details to review:
- Income Replacement: What percentage of your income is covered? Many policies replace approximately 50%–60%, often subject to a monthly maximum.
- Waiting Period: How long must you be unable to work before benefits begin?
- Benefit Duration: How long could payments continue?
- Definition of Disability: Does the policy cover you if you can't perform your specific occupation, or only if you're unable to work in other occupations as well?
- Tax Treatment: Would the benefits be taxable when received?
Why the Tax Treatment Matters
This last point is particularly important and often overlooked.
If your employer pays your disability insurance premiums and those premiums aren't included in your taxable income, benefits are generally taxable when received. The same generally applies if you pay the premiums through pre-tax payroll deductions. This means a policy advertising 60% income replacement could provide considerably less spendable income after taxes. Conversely, if you pay disability insurance premiums with after-tax dollars, the benefits are generally received tax-free.
Additionally, some employer policies calculate benefits using only your base salary, potentially excluding bonuses, commissions, or other compensation. Many also have monthly benefit caps that can limit coverage for higher earners.
Depending on your income, household expenses, and existing coverage, an individual disability insurance policy may be worth considering to help close the gap.
Before purchasing additional insurance, it is important to understand what you already have and determine whether it's sufficient to protect your family's financial needs.
5. Don't Forget Retirement and Other Benefits
Open enrollment is also a good reminder to revisit your retirement savings strategy.
At a minimum, review whether you're contributing enough to receive your employer's full 401(k), 403(b), or other retirement plan match.
If your cash flow has improved, consider increasing your contribution percentage for the upcoming year. Even a 1% increase each year can make a meaningful difference over time. It's also worth reviewing whether traditional pre-tax or Roth contributions make more sense based on your current and anticipated future tax situation.
Beyond retirement, don't overlook other benefits your employer may offer:
- Dependent Care FSA: Allows eligible employees to set aside pre-tax dollars for qualifying childcare or dependent care expenses. These benefits should also be coordinated with the Child and Dependent Care Tax Credit.
- Legal Assistance: Some employers offer legal plans that can help cover the cost of preparing wills, powers of attorney, and other estate planning documents.
- Employee Assistance and Wellness Programs: These may provide access to counseling, financial education, or other services at little or no additional cost.
These benefits are easy to overlook but may provide meaningful savings or services you're already paying for elsewhere.
Bringing It All Together
Your employee benefits are an important part of your overall financial plan. From managing healthcare expenses to protecting your income and saving for retirement, these decisions can have a meaningful impact on your financial future.
Open enrollment is a great opportunity to review what's available, identify potential gaps, and make sure your benefits align with your family's needs and long-term goals.
If navigating your employee benefits feels overwhelming, please reach out. I'd be happy to review your options with you and help you better understand the benefits you're choosing. You can schedule time by clicking here.
________________________________________
Disclaimer: This article is provided for educational and informational purposes only and does not constitute individualized financial, investment, tax, legal, or insurance advice. Tax laws, contribution limits, and insurance provisions are subject to change and may vary based on individual circumstances. Consult with appropriate qualified professionals before making financial decisions.